Review of Nectaro

Updated | October 2026
Profitability
Up to 15%
Type
P2B Business
Risk
(6/10)
Medium
Liquidity
No Liquidity
Regulated
Yes
Country
Latvia

InvantAPPs score

0/100

Breakdown by Category

Detailed scores for each area assessed

&nbsp0/20&nbsp
Significance within its sector
&nbsp0/10&nbsp
Ease of use and mobile app
&nbsp0/10&nbsp
Compound interest payable
&nbsp0/10&nbsp
Welcome bonus and referral bonus
&nbsp0/10&nbsp
Tax-friendly
&nbsp0/10&nbsp
Investment liquidity
&nbsp0/30&nbsp
Returns and fees

Features

Minimum investment:
50,00 €
Regulation:
IBF
Withdrawal fee:
Free
Payment methods:
Instantaneous · SEPA
Type of investor:
Private individual/Business
Suitability test:
Yes
Geographical exclusions:
Geographical exclusions: Residents of EEA countries only; residents outside the EEA are not eligible

Platform statistics

Assets under management
27.000.000,00 €
Updated: July 2026
Portfolio health:
Surveillance
Current loans: 81.2%
En mora/recuperación: 6.8%
16550
Investors

10

Years in active service
2016
Founded
Loans financed:
71.000.000,00 €
Average interest:
12.8%
Audited accounts:
Yes
Regulatory licence:
IBF

InvantAPPs Portfolio

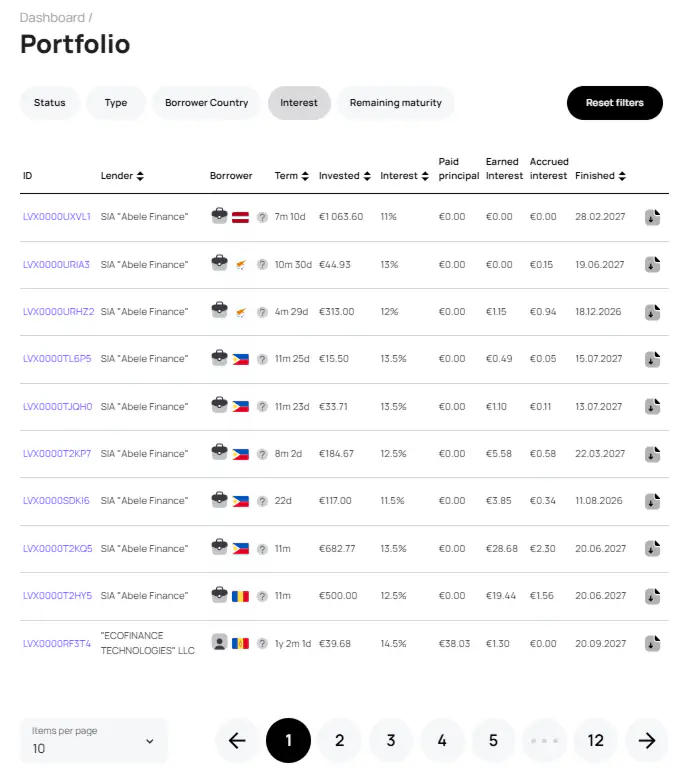
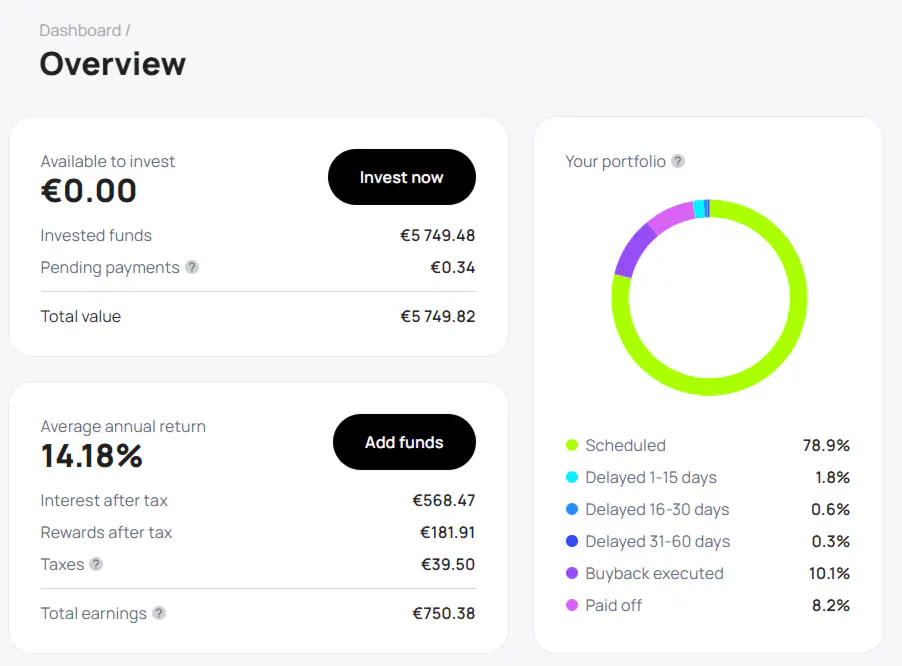
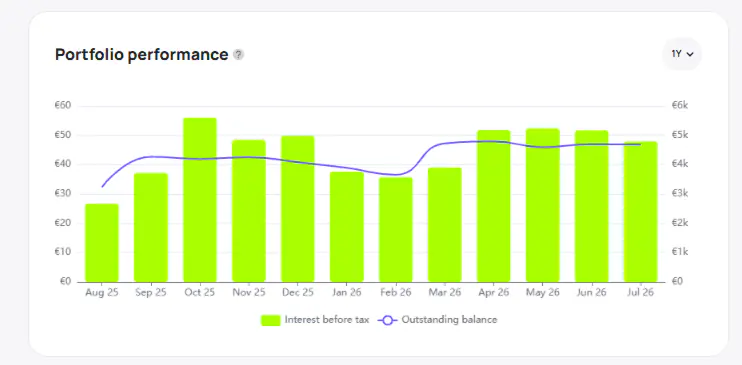
Total portfolio:
5.226,00 €

TIR:

14.47%
From:
January 2025
My current investment
Role in the portfolio:
Security
Suggested allocation:
3
-10

%

Dedication:
Bass
Surveillance:
Long term
Claim your bonus through our link
1% Additional
Join our Telegram community to ask questions and connect with other investors.

Videos about Nectaro

Taxation

Withholding tax:
Retains
Withholding rate:
5%
Tax-friendly:
Yes
Model 720:
Yes
Income Tax Category:
Share capital
Tax certificate:
Yes
Notes: For retail investors who are tax residents in EU/EEA countries other than Latvia, Nectaro applies a withholding tax of 5% on interest. Tax residents in Latvia are subject to 25.5%; residents outside the EEA are subject to 25.5%, subject to any possible reduction under a double taxation agreement; and residents of Lithuania may benefit from a withholding tax rate of 0% if they provide a certificate of tax residence. No withholding tax applies to legal entities. The tax statement can be requested by email, but no evidence has been found of a downloadable annual tax certificate with a breakdown for January to December. Nectaro indicates that the income is interest, not capital gains.

Liquidity

Early exit:
No
Average loan term:
3–60 months
Time to settle:
Not available
Notes: The Terms and Conditions permit the sale of Notes via a transfer order to another registered investor, but the investor must find the buyer independently. Nectaro warns that there may be no market available for a Note and that it may be necessary to hold it until maturity; the KID states that there is no active secondary market provided by Nectaro and that a sale may require a discount. No early exit mechanism was found whereby Nectaro would repay the capital early. Withdrawals are processed within up to 5 working days and the bank transfer may take up to a further 2 working days, but these only affect available funds, not pending investments. Nectaro reserves the right to delay or reject withdrawals in exceptional cases. No verifiable public data was found regarding actual sale times or historical instances of the mechanism being suspended.

Profitability

Stated return:
Up to 15%
Self-investment:
Yes
Payment frequency:
Variable

Regulation

Regulatory body:
Bank of Latvia
Competent authority:
Not available
Entry in the register:
Country of regulation:
Latvia
Regulated since:
March 2023
Notes: SIA Nectaro is authorised as an investment services firm (IBF), licence no. 27-55/2023/3, and is supervised by Latvijas Banka. The licence was granted on 29 March 2023. The platform operates under the MiFID framework and participates in the Latvian investor protection scheme, which may cover 90 % of irrevocable losses up to EUR 20,000. It does not operate under the European Crowdfunding Regulation (EU) 2020/1503 nor does it hold ECSP authorisation.

Guarantees and risk mitigation

A) Type of guarantee
Without security
▸Promissory notes are legally defined as unsecured obligations, and the underlying loans are primarily unsecured loans. There is a contractual obligation on the part of the originator to repurchase the notes early, as set out in the cooperation and sale and purchase agreements where this is specified as applicable in the final terms; this obligation is triggered after more than 60 days’ default and covers the outstanding principal, interest and other ancillary claims.
B) Stress scenario
▸The documents allow for the appointment of a backup administrator to continue managing the rights to collection should the originator be unable to do so. If Nectaro were to go into liquidation, a liquidator or administrator supervised by Latvijas Banka would take over the management of the accounts and portfolios of financial instruments in accordance with insolvency regulations.
▸The originator manages collections through reminders, potential restructuring arrangements and external debt collection agencies. If the borrower fails to pay and the originator is unable to recover the funds, the investor may lose some or all of their investment; where an early repayment obligation applies, the originator must repurchase the rights after more than 60 days’ default.
▸N/A
C) Additional guarantees
Yes
(60 days)
Originator
No
Yes
No
1% Additional
Claim your bonus through our link
1% Additional
Claim your bonus through our link

InvantAPPs Summary

What is Nectaro?

Nectaro is a regulated Latvian crowdlending platform that enables retail investors to invest in Series of Notes backed by consumer and corporate loans. With an estimated net annual return of 14.91% and a minimum investment of 50 euros, the platform channels funding to originators within its parent company, the Dyninno Group. It offers a buyback guarantee and an active secondary market, positioning itself as an attractive option within the regulated fintech sector for investors seeking to maximise their returns.

Launched in late 2023 in Riga (Latvia), Nectaro was established with a level of corporate backing that is unusual for a start-up crowdlending platform. Behind it stands the global giant Dyninno Group, a conglomerate founded in 2004 with over 5,000 employees and a presence in more than 50 countries across sectors such as tourism, entertainment and financial technology. Led by Sigita Kotlere, a professional with extensive previous experience at the well-known platform Mintos, Nectaro acts as the group’s internal financing arm, channelling capital from retail investors to its own credit originators under the EcoFinance brand, which operates primarily in Romania (Ecofinance IFN S.A.) and Moldova.

Nectaro’s business model is based on acting as a captive financing channel. This means that the platform does not prioritise individual profitability; in fact, it recorded corporate losses of 1.42 million euros due to the duplication of its marketing and staff costs in order to gain market share. At InvantAPPs, we believe this should not alarm investors, as it is common practice among platforms affiliated with a single business group: the actual profits are consolidated at parent company level thanks to the spread between the interest charged to end borrowers and the coupon paid to crowdlending investors. Therefore, Nectaro’s solvency depends directly on the financial health of the Dyninno Group.

The management team’s transparency is remarkable, with frequent reports and clear communication on the portfolio’s performance. However, in our view, a significant weakness is that SIA Nectaro’s annual accounts have not yet been audited by independent firms, a standard we consider necessary to build long-term trust, particularly as this is an entity holding an investment brokerage firm (IBF) licence regulated by Latvijas Banka.

The platform’s recent growth has been outstanding, with over 16,000 registered investors and a cumulative volume of funded loans exceeding 70 million euros as at July 2026, with a managed portfolio of around 27 million euros. To address the lack of liquidity that was holding back longer-term loans — such as Moldovan credit lines, which can run for up to five years — Nectaro has an integrated secondary market. This represents a substantial operational improvement, allowing shares to be sold before maturity if an investor needs to recover their capital early.

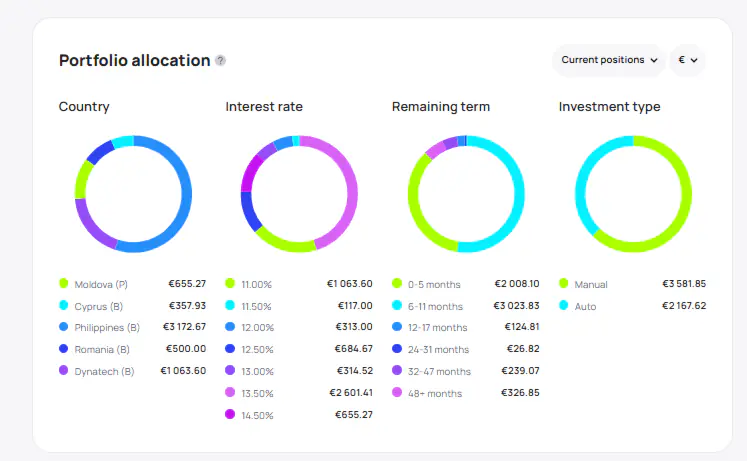
At InvantAPPs, we regard Nectaro as an excellent option for diversifying and boosting the average return on a crowdlending portfolio, offering an estimated net annual return of 14.91%. However, we would point out that the concentration risk is very high: the investor is almost entirely dependent on the creditworthiness of the Dyninno group. Whilst there is a buy-back guarantee that is triggered on the 61st day of arrears, this mechanism is not backed by actual collateral, but rather by a buy-back commitment from the originator within the same group. We therefore recommend treating Nectaro as a high-yield satellite position within a diversified portfolio, avoiding the concentration of a substantial portion of funds in it.

Key points

Robust regulation under an IBF licence, supervised by the Bank of Latvia (Latvijas Banka), and investor protection of up to 20,000 euros.
An excellent estimated net yield of 14.91% per annum, one of the most competitive on the current regulated market.
High risk of concentration of originators, as the bank relies almost exclusively on the group’s own credit subsidiaries (EcoFinance).
The platform’s annual accounts are not audited by an independent external firm, which reduces transparency regarding its actual financial position.
Withholding tax at source at a rate of 5% for Spanish investors, which can be claimed as a deduction on their personal income tax return.

Pros and cons

High average returns, with an estimated net interest rate of 14.91% per annum, outperforming most regulated competitors in the eurozone.
Financial backing from the Dyninno Group, a well-established global conglomerate with over 20 years’ experience and a presence in 50 countries.
An automatic buyback guarantee after 60 days covering the principal and accrued interest on loans in arrears.
Availability of a secondary market to provide early liquidity for long-term investments, such as 5-year Moldovan loans.
Single-group risk arising from the fact that virtually the entire supply is concentrated amongst EcoFinance’s originators (Romania and Moldova), with no diversification across external firms.
Withholding tax at source under code 5%, which requires additional formalities to avoid international double taxation when filing your personal income tax return.
The platform has not been subject to an external audit, which undermines transparency regarding the development of its internal financial statements in relation to regulatory oversight.

Experience and social proof

Trustpilot

32 Reviews
3.6/5

ScamAdviser

0%
Trust score: 100/100
Updated: July 2026

Social media activity

🟡 Not very active
⚪ No profile
🟡 Not very active
⚪ No profile
🟡 Not very active
🔵 Active

Alternatives to Nectaro

If Nectaro doesn’t suit your profile, here are the highest-rated alternatives in the sector
0/100
Profitability:
Up to 14%
Risk:
Medium
(6/10)
Regulated:
Yes
0/100
Profitability:
Up to 15%
Risk:
Medium
(5/10)
Regulated:
Yes
0/100
Profitability:
Up to 10,52%
Risk:
Medium
(6.5/10)
Regulated:
No

Frequently Asked Questions

Is NECTARO safe?

Yes, NECTARO is a secure platform that is directly supervised by Latvijas Banka under the MiFID regulatory framework and holds an investment brokerage firm (IBF) licence. Furthermore, investments are protected by Latvia’s state compensation scheme, which covers 90% of irrevocable losses up to a limit of 20,000 euros. It offers a 60-day buyback guarantee and has maintained a historical capital loss rate of 0% since its launch in 2023.

How much should I invest in NECTARO?

You should invest a moderate proportion of your portfolio in NECTARO, with a recommended limit of between 5% and 10% of the total capital allocated to crowdlending. The minimum investment is just 50 euros, which makes internal diversification much easier. Given that the loan offering is mainly concentrated on originators within its own corporate group (EcoFinance), a prudent ‘satellite’ approach protects your overall portfolio from systemic concentration risks.

How do I declare interest from NECTARO on my income tax return?

Interest earned on NECTARO is taxed in Spain as investment income within the savings tax base, at tax rates ranging from 19% to 28%. The platform applies an automatic withholding tax of 5% to Spanish residents, which you must declare in the international double taxation box on your personal income tax return in order to claim a deduction and avoid double taxation. It does not issue an automatically downloadable annual tax certificate, so you must request your details by email or check your transaction statement. We recommend verifying the information with a tax adviser.

What happens if NECTARO closes down?

In the event of NECTARO’s bankruptcy or closure, users’ uninvested capital is segregated from the platform’s operational accounts and would be returned to them in full. As a regulated investment brokerage firm (IBF), there is a business continuity plan managed under the supervision of the Bank of Latvia to ensure the collection and orderly settlement of active Note Series. In the worst-case scenario of fraud or insolvency, the state investor compensation scheme would cover losses up to 20,000 euros.

How does the buy-back guarantee scheme work at NECTARO?

The buyback guarantee, or 'buyback obligation', is automatically triggered on the 61st day of arrears on payments for the underlying loan. The originator (such as Ecofinance IFN S.A.) repurchases the investment, returning the principal invested together with all interest accrued up to that date. This guarantee is backed at corporate level by the parent company’s fintech group, Dyninno Group.

Does NECTARO charge fees to investors?

No, NECTARO does not charge retail investors any commission on their core transactions. Account registration, manual or automatic investing (Auto-invest), use of the secondary market and cash withdrawals to your bank account are completely free of charge. The platform generates revenue through the spread and the fees it charges internally to group companies.

Contact and support

Email: support@nectaro.eu
Telephone: +371 67783589
They provide service in Spanish:
No
Live chat:
No
Telegram:
No
Response time:
+3 days
Official FAQ:

Corporate identity

Legal name:
SIA Nectaro
Country of registration:
Latvia
Registration code:
40203016025
Registered office:
1 Jeruzalemes iela, Riga, LV-1010, Latvia
Work email:
support@nectaro.eu

Regulation and equipment

Licence type:
IBF
Management team
Board Member & Chief Executive Officer
Sigita Kotlere
Board Member & CCO
Igors Petrovs
Founder & Board Member
Dmitry Tsymber
Verified profiles:
Yes

About the author

Antonio Hernández – Founder of InvantApps

Antonio Hernández

Engineer, economist and founder of Invant APPs. I help you achieve financial freedom through smart investing and passive income.

Legal notice

Investing in crowdlending and crowdfunding involves risks, including the partial or total loss of the capital invested, and past performance is no guarantee of future results. The content on this site is for information purposes only and reflects our personal experience and opinion: it does not constitute financial or tax advice. Some links are affiliate links; the platform pays us a commission, which does not incur any cost to you nor does it influence our analysis.