Review of Debitum
InvantAPPs score
- Excellent
Breakdown by Category
Detailed scores for each area assessed
Features
Platform statistics
7
InvantAPPs Portfolio
- Active Investment
TIR:
Security: A regulated platform or one with a long track record in the sector.
Liquidity: A platform where funds can be withdrawn quickly.
Returns: A platform offering high returns but carrying a higher level of risk.
%
% of the total recommended P2P capital
Time required for active management
Taxation
Liquidity
Profitability
Regulation
- Licensed
Guarantees and risk mitigation
The loan is secured against a tangible asset (property, vehicle, machinery) which can be repossessed and sold to recover your money if the borrower defaults
Main type
The originator undertakes to buy back the loan from you if the borrower is more than X days in arrears, repaying you the principal and interest. This is subject to the originator remaining solvent.
Buyback
A financial buffer that the platform sets aside from its own commission to cover defaults before they affect you. Its effectiveness depends on its actual size relative to the total amount lent.
Reserve fund
The originator invests a portion of its own capital in the same loan or portfolio alongside the investors, thereby aligning its interests with those of the investors in ensuring that the loan is repaid in full.
Skin in the game
Your uninvested money is held in an account separate from the company’s balance sheet, at a bank or regulated payment institution. If the platform goes bankrupt, that money is not included in the distribution to its creditors.
Segregation of accounts
InvantAPPs Summary
What is Debitum?
Debitum Investments is a Latvian P2B crowdlending platform, founded in 2019 and regulated by the Bank of Latvia, which enables investment in commercial loans and financing for small and medium-sized enterprises (SMEs). With an average interest rate of 14.83% and a minimum investment of 10 euros, it is ideal for moderate-risk investors seeking to diversify their portfolio beyond traditional consumer credit whilst supporting the real economy.
Through this honest analysis, we assess the security of its regulated assets, its impeccable default rate of 0% and its liquidity conditions.
At InvantAPPs, we like to analyse crowdlending and crowdfunding without mincing our words, and after travelling to Riga in person to visit their headquarters, our views on the platform have taken a radical turn. We have to admit it: we used to see strict regulation as a bureaucratic burden that largely served to reduce investors" returns, but being there has completely changed our perspective. In Spain, the regulator and the tax authorities are often perceived as the "enemy’ out to get you, driven purely by a desire to raise revenue and imposing obstacles that make life difficult for start-ups. In Latvia, the political reality is the exact opposite. There, the regulatory bodies do not seek to bankrupt or crush companies; they work side by side within a framework of constructive cooperation to provide stability, transparency and a level playing field. The CEOs of competing platforms themselves cooperate with one another rather than trying to destroy each other, recognising that a strong, regulated ecosystem protects them all from situations that could undermine collective trust.
It is true that maintaining this IBF licence under the European MiFID II directive requires an administrative effort which inevitably results in slightly lower interest rates for us. However, given the current macroeconomic climate, this slight loss in profitability is a price we are happy to pay in exchange for impeccable institutional stability and a scheme offering genuine protection of up to €20,000 per investor against insolvency.
Another factor that motivated us to increase our investment in this P2B crowdlending platform was a crucial corporate change that took place in March 2026: Ingus Janums, the sole shareholder and beneficial owner of the company, stepped up and took on the role of CEO. In business, we love to apply a guiding principle: we invest where the board of directors puts their own money on the line. Knowing that the owner is directly at the helm and feels the full brunt of every outcome brings a remarkable alignment of interests to the platform. This philosophy translates into an unprecedented level of transparency; the company has set a new benchmark by publishing not only its audited annual results for 2025, but also the audited financial statements of all its credit-originating partners.
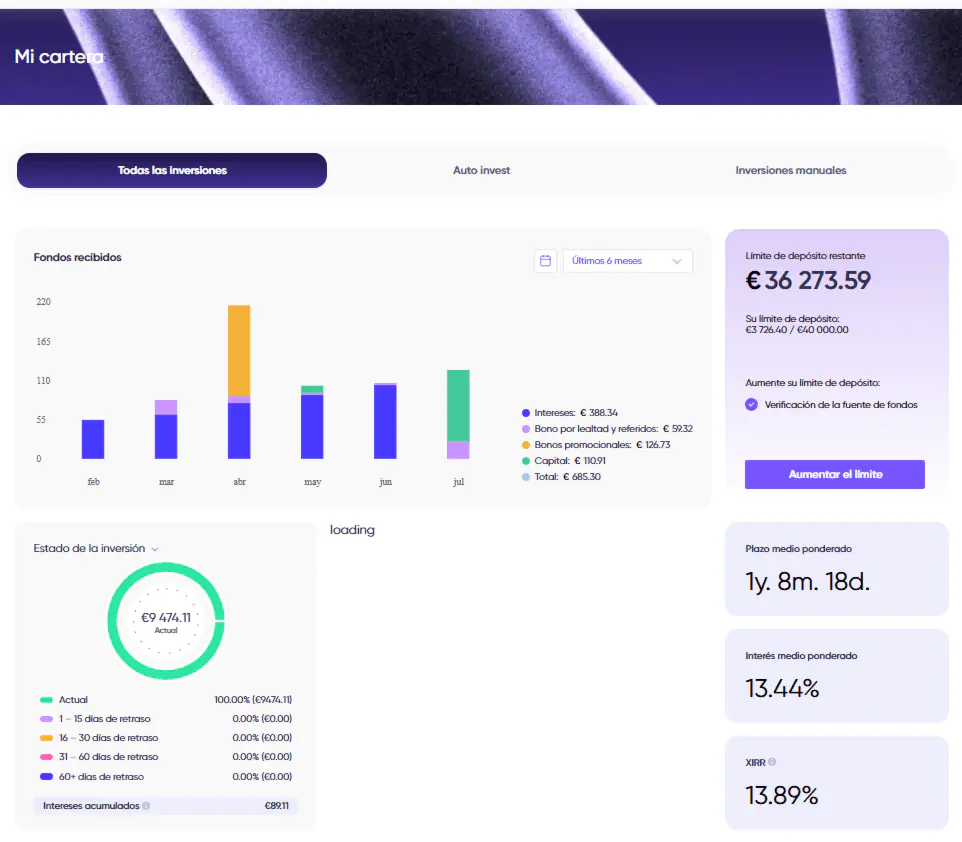
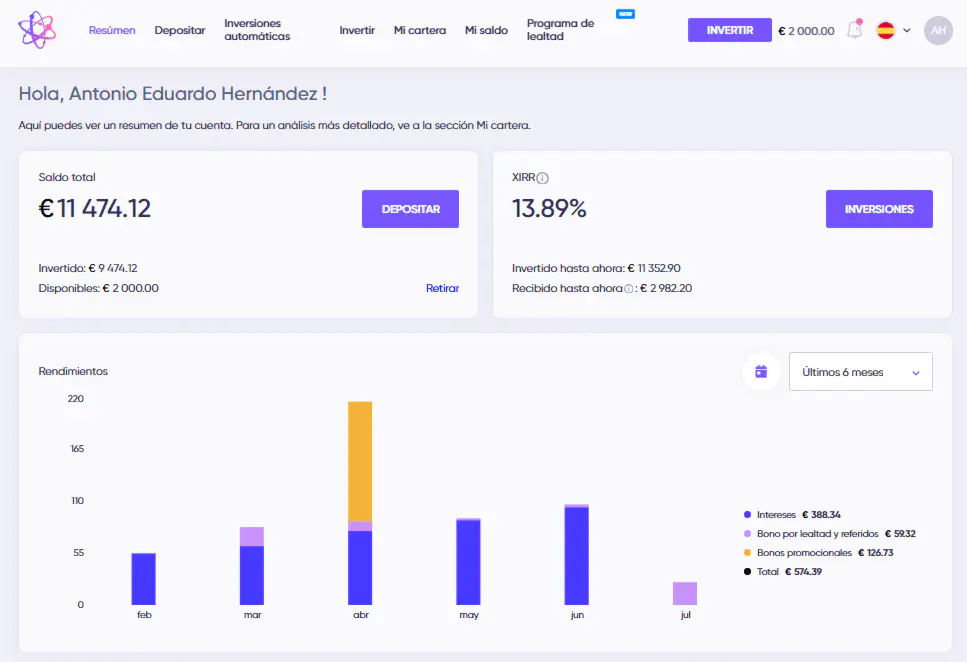
As for the performance of our actual portfolio in the channel, the figures underscore the strength of the project. In April 2026, we were managing a position of €6,600, and by June we had confidently increased this to over €9,400, setting ourselves the medium-term target of achieving a buffer of between €15,000 and €20,000. Debitum Investments has a global active portfolio of €67.43 million and a historical default rate of 0% as at July 2026. Its portfolio focuses on commercial loans backed by the real economy. We were able to visit the operations of its flagship originators, Latvian Forest (part of the Blatman Fund) and Baltic Terra, at the port of Riga. In northern Europe, timber is a veritable religion; forests cover between 40% and 75% of the land area, and the material provides thermal insulation up to 15 times better than concrete, ensuring an inexhaustible and counter-cyclical flow of business.
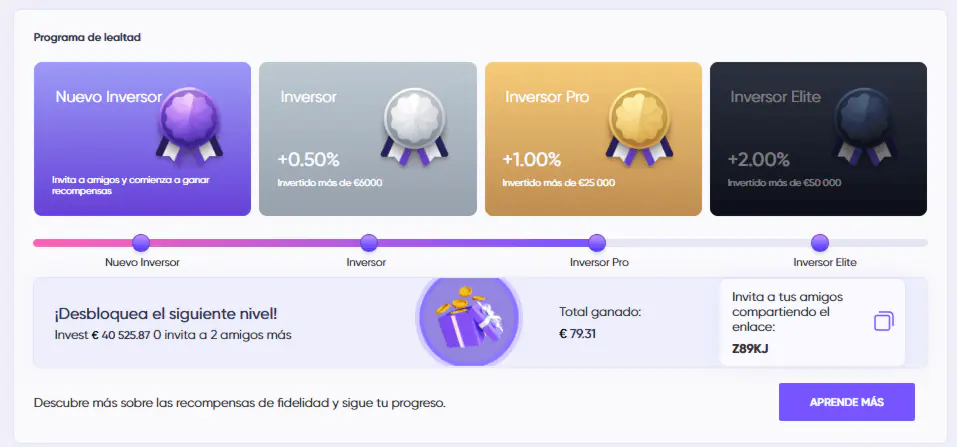
But as we’re always honest, you need to be aware of the real caveats before you learn how to start investing in Debitum. The platform has no secondary market or early exit option, which means your capital will be locked away until the exact maturity date of the notes. Furthermore, the buyback guarantee does not fall directly on the platform’s balance sheet; rather, it is a contractual buyback obligation of each originator (such as SIA Sandbox Funding), subject to a penalty of up to 15% in late payment interest if they fall behind, which deters them from defaulting. In the past, they experienced a minor delay of Triple Dragon, but corporate communication was impeccable and transparent. Finally, bear in mind the mandatory 5% withholding tax at source for eurozone residents. To start trading successfully, you simply need to register, pass the identity verification process and activate their Auto-Invest feature, or manually select short-term notes (such as the attractive 3-month notes at 11% interest) or take full advantage of their 15% annual rates if you achieve 'Pro' status in their loyalty programme.
Key points
Pros and cons
Experience and social proof
Social media activity
- YouTube
Alternatives to Debitum
Frequently Asked Questions
Is Debitum Investments safe?
How much should I invest in Debitum Investments?
How do I declare interest on Debitum?
What happens if Debitum goes bankrupt?
Is there liquidity or a secondary market?
How are profits from Debitum taxed by the Spanish tax authorities?
How exactly does the buyback guarantee work?
Contact and support
- High accessibility
Legal information
Corporate identity
Regulation and equipment
- The information is taken from public sources and may not be up to date. Always check the official website.
About the author
Antonio Hernández
Engineer, economist and founder of Invant APPs. I help you achieve financial freedom through smart investing and passive income.
Legal notice
Investing in crowdlending and crowdfunding involves risks, including the partial or total loss of the capital invested, and past performance is no guarantee of future results. The content on this site is for information purposes only and reflects our personal experience and opinion: it does not constitute financial or tax advice. Some links are affiliate links; the platform pays us a commission, which does not incur any cost to you nor does it influence our analysis.