Review of Loanch
InvantAPPs score
- Excellent
Breakdown by Category
Detailed scores for each area assessed
Features
Platform statistics
4
InvantAPPs Portfolio
- Active Investment
TIR:
Security: A regulated platform or one with a long track record in the sector.
Liquidity: A platform where funds can be withdrawn quickly.
Returns: A platform offering high returns but carrying a higher level of risk.
%
% of the total recommended P2P capital
Time required for active management
Taxation
Liquidity
Profitability
Regulation
- Unregulated
Guarantees and risk mitigation
The loan is secured against a tangible asset (property, vehicle, machinery) which can be repossessed and sold to recover your money if the borrower defaults
Main type
The originator undertakes to buy back the loan from you if the borrower is more than X days in arrears, repaying you the principal and interest. This is subject to the originator remaining solvent.
Buyback
A financial buffer that the platform sets aside from its own commission to cover defaults before they affect you. Its effectiveness depends on its actual size relative to the total amount lent.
Reserve fund
The originator invests a portion of its own capital in the same loan or portfolio alongside the investors, thereby aligning its interests with those of the investors in ensuring that the loan is repaid in full.
Skin in the game
Your uninvested money is held in an account separate from the company’s balance sheet, at a bank or regulated payment institution. If the platform goes bankrupt, that money is not included in the distribution to its creditors.
Segregation of accounts
InvantAPPs Summary
What is Loanch?
LOANCH is a P2P lending investment platform that connects investors with short-term consumer microloans in emerging markets such as Malaysia, and stands out for its strict 30-day buy-back guarantee. Operating since 2022 with a minimum investment of just €10, it offers annual returns of between 13.6% and 16% through its Auto-Invest feature. Although it is unregulated, we believe it is worth taking the risk to invest in Loanch, following its recent operational restructuring.
At InvantAPPs, we believe that investing in Loanch is currently one of the most profitable strategies, but also one of the most speculative and high-risk within our crowdlending radar. We do not wish to be lukewarm in our analysis: the platform has just emerged from an extremely critical operational situation that has shifted market sentiment. In early 2026, its main payment provider in Poland, Quicko, lost its regulatory licence, freezing deposits and withdrawals for three agonising months. Rumours of a scam or Ponzi scheme abounded across social media channels and online communities. However, our stance was always clear: keep a cool head, face up to the situation and let the work continue. The management of the P2P platform responded by implementing a comprehensive migration to Multipass as its primary payment gateway (adding redundancy for the future) and by changing its legal jurisdiction from Hungary to Croatia.
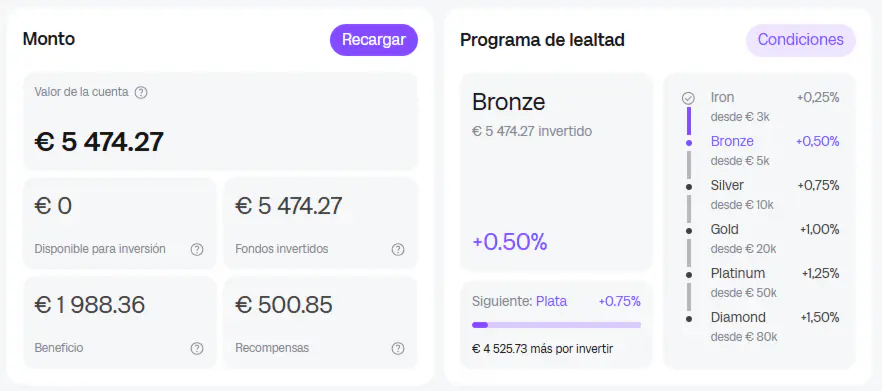
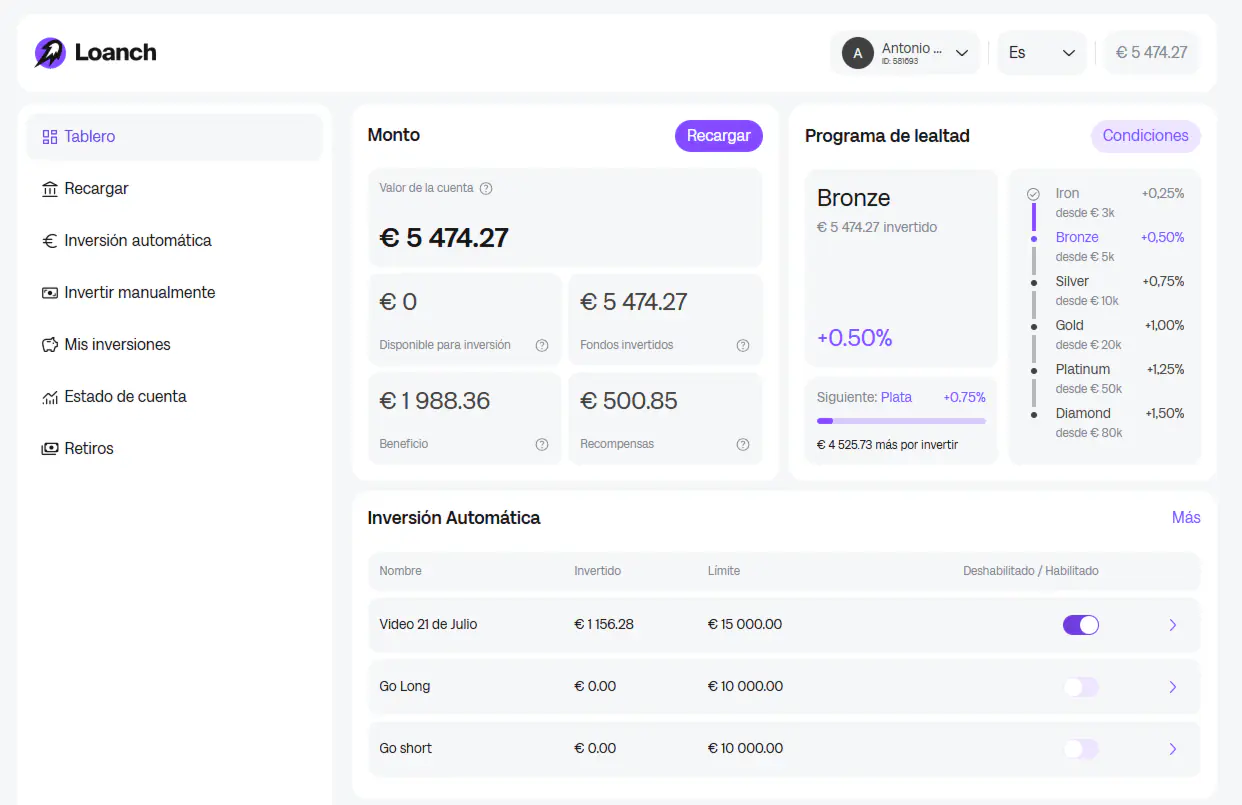
From the perspective of our own portfolio, risk management on this platform has been extremely dynamic. We managed peaks of €26,579 invested, taking advantage of aggressive cashback campaigns for 3% and 4% (earning bonuses of up to €465 in one go) and Auto-Invest settings optimised at 15% and 16%.
However, let’s be honest: the current risk profile has become more acute due to a key concentration factor that you need to be aware of if you’re looking for reviews of Loanch. The originator Amana (Indonesia) has withdrawn from the catalogue, leaving Tambadana (Malaysia) as the sole loan-issuing platform available, with around 60,000 active contracts. This means that if Tambadana suffers a mass default or goes bankrupt, the entire structure collapses. Furthermore, following the stabilisation of the payment gateway, interest rates have been adjusted to around 14.5% for both manual and automatic investments (Go Short strategy).
Despite the lack of regulation under the ECSP licence, we regard this ecosystem as a powerful tool for maximising compound interest in the short term. Its 30-day buyback guarantee is amongst the strictest and fastest in the entire global P2P market. If you are prepared to accept the volatility and understand that such a high return always carries a commensurate risk.
Key points
Pros and cons
Experience and social proof
Social media activity
- YouTube
Alternatives to Loanch
Frequently Asked Questions
What happened with Loanch in 2026, and how was it resolved?
What is the key advantage that sets Loanch apart?
Does Loanch have a secondary market?
Contact and support
- High accessibility
Legal information
Corporate identity
Regulation and equipment
- The information is taken from public sources and may not be up to date. Always check the official website.
About the author
Antonio Hernández
Engineer, economist and founder of Invant APPs. I help you achieve financial freedom through smart investing and passive income.
Legal notice
Investing in crowdlending and crowdfunding involves risks, including the partial or total loss of the capital invested, and past performance is no guarantee of future results. The content on this site is for information purposes only and reflects our personal experience and opinion: it does not constitute financial or tax advice. Some links are affiliate links; the platform pays us a commission, which does not incur any cost to you nor does it influence our analysis.