Review of Income Marketplace

Top 3 Returns (-90 Days)
Updated | October 2026
Profitability
Up to 15%
Type
P2B Business
Risk
(6/10)
Medium
Liquidity
No Liquidity
Regulated
No
Country
Estonia

InvantAPPs score

Breakdown by Category

Detailed scores for each area assessed

&nbsp0/20&nbsp
Significance within its sector
&nbsp0/10&nbsp
Ease of use and mobile app
&nbsp0/10&nbsp
Compound interest payable
&nbsp0/10&nbsp
Welcome bonus and referral bonus
&nbsp0/10&nbsp
Tax-friendly
&nbsp0/10&nbsp
Investment liquidity
&nbsp0/30&nbsp
Returns and fees

Features

Minimum investment:
10,00 €
Regulation:
Unlicensed
Withdrawal fee:
Free
Payment methods:
Instantaneous · SEPA
Type of investor:
Private individual/Business
Suitability test:
Yes
Geographical exclusions:
Geographical exclusions: EEA residents only

Platform statistics

Assets under management
25.000.000,00 €
Updated: July 2026
10452
Investors

6

Years in active service
2020
Founded
Loans financed:
228.722.999,00 €
Average interest:
13.5%
Audited accounts:
Yes
Regulatory licence:
Unlicensed

InvantAPPs Portfolio

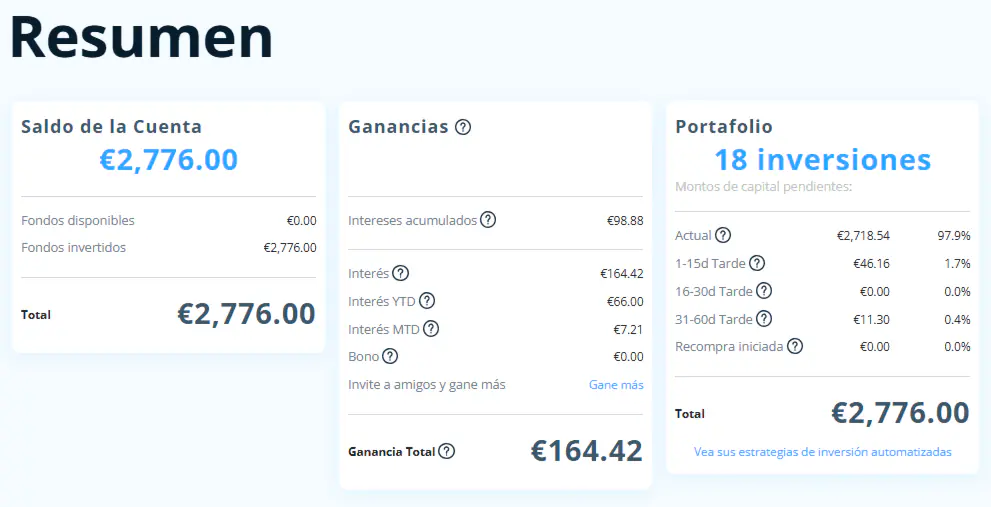
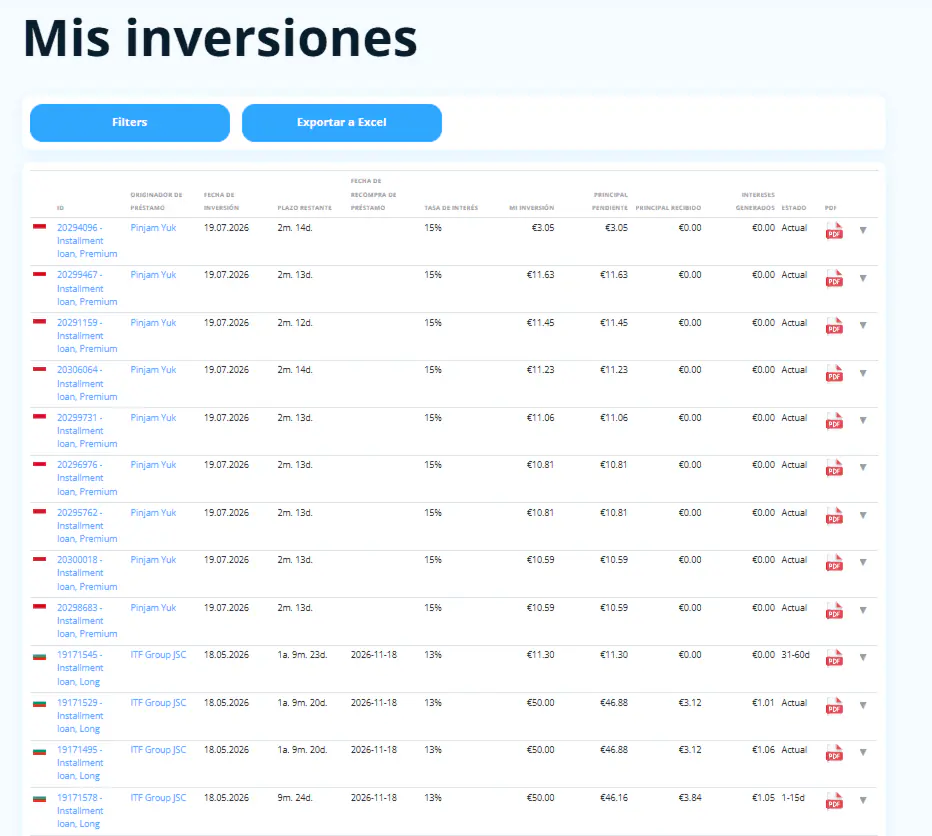
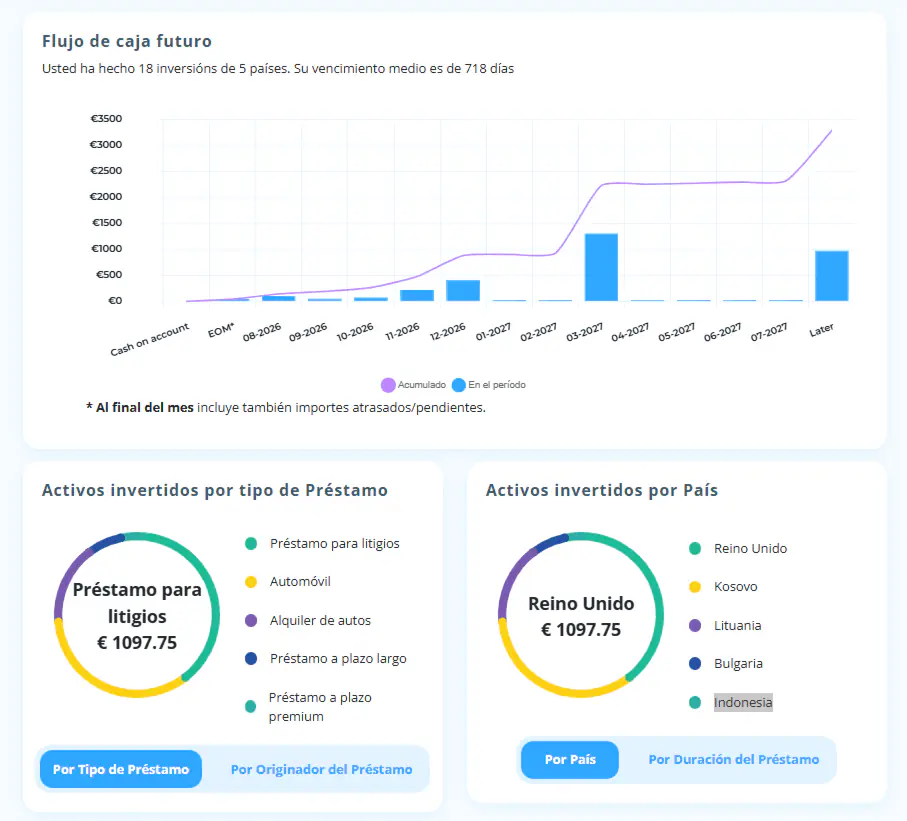
Total portfolio:
2.810,00 €

TIR:

13.20%
From:
February 2024
My current investment
Role in the portfolio:
Security
Suggested allocation:
3
-7

%

Dedication:
Bass
Surveillance:
Long term
Claim your bonus through our link
1% Additional
Join our Telegram community to ask questions and connect with other investors.

Taxation

Withholding tax:
It does not retain
Tax-friendly:
Yes
Model 720:
No
Income Tax Category:
Share capital
Tax certificate:
Yes
Notes: Income does not withhold tax on returns; the investor is responsible for declaring them in their country of residence. It does not count towards Form 720 for the Spanish tax authorities.

Liquidity

Early exit:
No
Average loan term:
3–60 months
Time to settle:
On maturity
Notes: There is currently no secondary market for selling positions to other investors. No public evidence was found of a suspension of the Early Buyback scheme or of an operational secondary market; the absence of a secondary market continued to be documented in 2026. Cases of default or prolonged recovery do not constitute liquidity mechanisms.

Profitability

Stated return:
Up to 15%
Self-investment:
Yes
Payment frequency:
Monthly

Regulation

Competent authority:
Not available
Notes: Income states that it is not regulated by a financial authority. Its activities do not fall within the scope of financial services regulated under current Estonian legislation, and Regulation (EU) 2020/1503 does not apply to its direct investment model in loans. In 2026, Estonia still has no specific regulation for the sector, and the platform is assessing regulatory options in neighbouring countries.

Guarantees and risk mitigation

A) Type of guarantee
Pledge (movable property)
▸Income describes two structures: a direct assignment with a subordinated stake held by the originator, and a pledge structure over the originator’s loan portfolio in favour of an Income SPV. Furthermore, it states that the originator is contractually obliged to repurchase loans more than 60 days past due, paying the full principal and accrued interest; the binding legal documentation could not be publicly verified.
B) Stress scenario
▸If an originator defaults or goes into administration, Income states that it takes control of the originator’s portfolio and uses the originator’s collections, profits and subordinated interest to repay investors’ principal and interest first. Investors’ funds are held in segregated accounts, according to the FAQs.
▸N/A
C) Additional guarantees
Yes
(60 days)
Originator
No
Yes
No
1% Additional
Claim your bonus through our link
1% Additional
Claim your bonus through our link

InvantAPPs Summary

What is Income Marketplace?

INCOME is an Estonian crowdlending platform founded in 2020 that operates as a global lending marketplace where users can invest in consumer loans from various international originators. The platform offers attractive average returns of around 13.51% per annum as at May 2026, with a minimum investment of just 10 euros. It is particularly aimed at investors who prioritise active management of originator risk over immediate liquidity.

Since its launch in 2020, INCOME has accumulated a total funded volume exceeding 228 million euros, building up an active portfolio of 25 million euros as at May 2026 with more than 10,300 registered investors. The platform’s great value lies in its innovative security architecture, notably the 'Junior Share' (where the originator bears the first losses on a subordinated basis) and the 'Cashflow Buffer' to protect investors in the event of an originator’s failure. However, it has obvious limitations: it operates without a regulatory licence in Estonia, as the ECSP Regulation does not apply to its direct credit sales model, and its financial statements remain unaudited. Furthermore, there is no secondary market for selling shares before their average maturity of 12 months, although certain loans offer variable early exit options from the first month onwards. At InvantAPPs, we consider that, despite having slow customer support – which often takes more than three days to respond – and certain complaints about glitches in its mobile app, its multi-layered protection model is technically one of the most robust in the sector.

Key points

An advanced security structure featuring 'Junior Share' and 'Cashflow Buffer' to effectively mitigate the risk of originator insolvency.
It does not hold an official regulatory licence and operates without supervision by the Estonian financial authority.
There is no structured secondary market, which reduces the immediate liquidity of long-term investments.
The platform has recorded a cumulative total volume of over 228 million euros and manages 25 million euros in assets as at May 2026.

Pros and cons

A pioneering multi-layered protection model that includes a 60-day buyback guarantee alongside a subordinated cash flow buffer.
The average interest rate on the portfolio is 13.51% per annum, which is highly competitive within the international crowdlending sector.
No fees whatsoever for depositing, investing or withdrawing funds, maximising the investor’s net return from as little as 10 euros.
There is no active secondary market for guaranteed and rapid early redemption.
A platform not regulated under the European ECSP framework, with annual financial statements that have not been externally audited.
Slow customer support, with response times exceeding three days, and reports of occasional instability in its mobile app.

Experience and social proof

Trustpilot

60 Reviews
3.8/5

ScamAdviser

0%
Trust score: 94/100
Updated: July 2026

Social media activity

🟡 Not very active
⚪ No profile
🟡 Not very active
🟡 Not very active
⚪ No profile
🟡 Not very active

Alternatives to Income Marketplace
If Income Marketplace doesn’t suit your profile, these are the highest-rated alternatives in the sector
0/100
Profitability:
Up to 14%
Risk:
Medium
(6/10)
Regulated:
Yes
0/100
Profitability:
Up to 15%
Risk:
Medium
(5/10)
Regulated:
Yes
0/100
Profitability:
Up to 6%
Risk:
Bass
(8/10)
Regulated:
No

Frequently Asked Questions

Is INCOME safe?

INCOME’s security lies in its private guarantees, not in licences, as it is not regulated. It offers a 60-day buy-back option, a subordinated 'Junior Share' and a 'Cashflow Buffer' that protects your capital should a credit originator go bankrupt.

How much should I invest in INCOME?

INCOME requires a minimum of 10 euros per loan. Due to its risk profile, which is driven by global originators, and the lack of formal regulation, we recommend allocating a maximum of 10% of your total crowdlending portfolio to maintain diversification.

How do I declare interest on INCOME?

Interest earned on INCOME is declared on your personal income tax return as investment income within the savings tax base (19%–28%). The platform does not deduct tax at source, and investors must declare their earnings manually.

What happens if INCOME closes down?

If INCOME goes into administration, investors' claims are protected by the collateral held over the originators' portfolios. The credit agreements are entered into directly with the originators and remain in force on a segregated basis.

What is INCOME’s 'Cashflow Buffer'?

It is a mechanism that redirects loan repayments directly to investors in the event that an originator goes bankrupt. This ensures that your capital is repaid with absolute priority over any other claims against the originator.

Contact and support

Email: hello@getincome.com
Telephone: +372 5698 9517
They provide service in Spanish:
No
Live chat:
No
Telegram:
No
Response time:
+3 days
Official FAQ:

Corporate identity

Legal name:
Income Company OÜ
Country of registration:
Estonia
Registration code:
16014116
Registered office:
Harju County, Tallinn, Kesklinna district, Tornimäe Street 3 // 5 // 7, 10145, Estonia
Work email:
16014116@eesti.ee

Regulation and equipment

Licence type:
Unlicensed
Management team
CEO
Lavrenti Chudakov
Member of the management board
Alexander Hauptmann
Verified profiles:
Yes

About the author

Antonio Hernández – Founder of InvantApps

Antonio Hernández

Engineer, economist and founder of Invant APPs. I help you achieve financial freedom through smart investing and passive income.

Legal notice

Investing in crowdlending and crowdfunding involves risks, including the partial or total loss of the capital invested, and past performance is no guarantee of future results. The content on this site is for information purposes only and reflects our personal experience and opinion: it does not constitute financial or tax advice. Some links are affiliate links; the platform pays us a commission, which does not incur any cost to you nor does it influence our analysis.