Review of Finforta
InvantAPPs score
- Regular
Breakdown by Category
Detailed scores for each area assessed
Features
Platform statistics
1
InvantAPPs Portfolio
- No investment
Security: A regulated platform or one with a long track record in the sector.
Liquidity: A platform where funds can be withdrawn quickly.
Returns: A platform offering high returns but carrying a higher level of risk.
%
% of the total recommended P2P capital
Time required for active management
Videos about Finforta
Taxation
Liquidity
Profitability
Regulation
- Unregulated
Guarantees and risk mitigation
The loan is secured against a tangible asset (property, vehicle, machinery) which can be repossessed and sold to recover your money if the borrower defaults
Main type
The originator undertakes to buy back the loan from you if the borrower is more than X days in arrears, repaying you the principal and interest. This is subject to the originator remaining solvent.
Buyback
A financial buffer that the platform sets aside from its own commission to cover defaults before they affect you. Its effectiveness depends on its actual size relative to the total amount lent.
Reserve fund
The originator invests a portion of its own capital in the same loan or portfolio alongside the investors, thereby aligning its interests with those of the investors in ensuring that the loan is repaid in full.
Skin in the game
Your uninvested money is held in an account separate from the company’s balance sheet, at a bank or regulated payment institution. If the platform goes bankrupt, that money is not included in the distribution to its creditors.
Segregation of accounts
InvantAPPs Summary
What is Finforta?
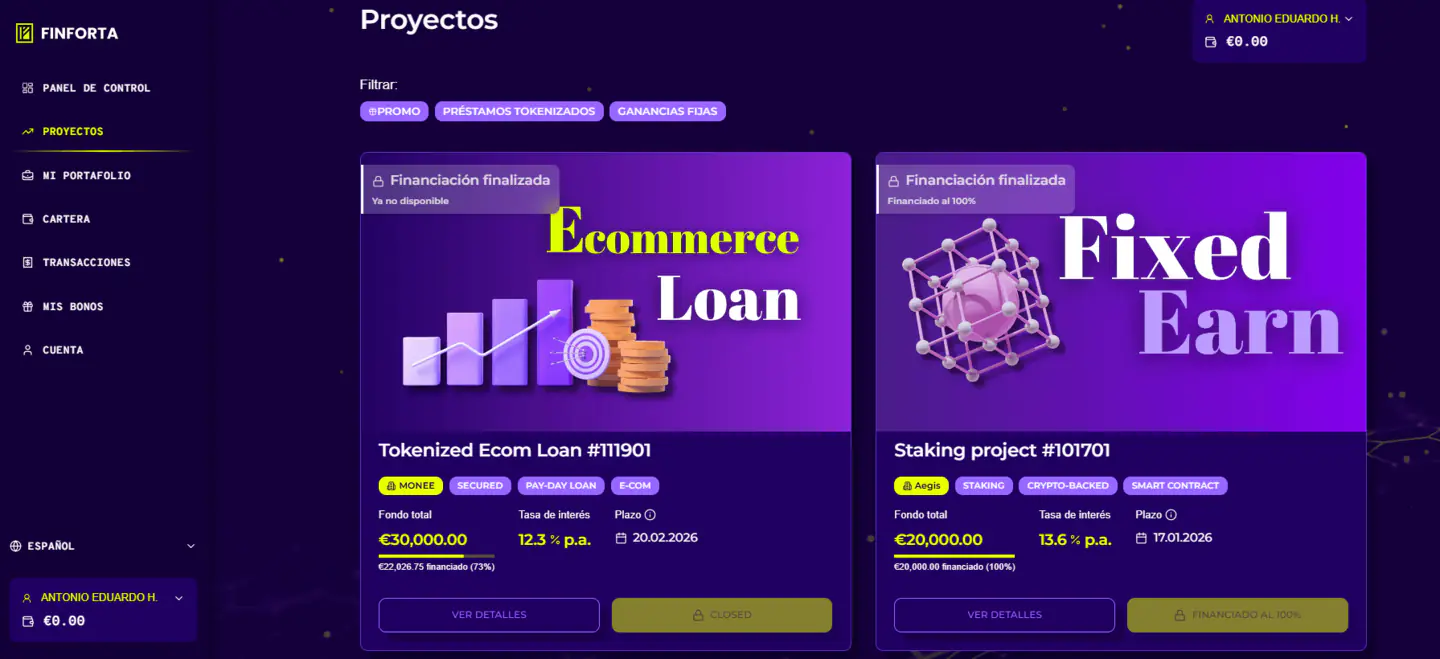
FINFORTA is a crowdlending platform of Czech and Spanish origin, founded in 2024, which enables investment in e-commerce loans and loans backed by crypto collateral. It offers an average annualised return of up to 13% on very short-term projects (from 14 days), with the distinctive feature that it does not involve a traditional buyback guarantee or real estate mortgages. It is an option designed for risk-tolerant investors seeking niche diversification and rapid liquidity through a straightforward process in euros.
FINFORTA is a platform launched in 2024 with a geographically hybrid approach, operating under the brand Finance & Assets, s.r.o. in Prague and with a presence in Spain through the limited company FINFORTA SL, based in Barcelona. Its technological offering is closely intertwined with other projects within the Baltic crypto and crowdlending ecosystem, such as FF Forest, with which it shares not only the technical software development team but also a significant part of its management team and philosophy. Its approach centres on structuring investment options denominated in euros but linked to e-commerce assets and loans collateralised by crypto-assets.
FINFORTA’s business model is based on acting as a financial intermediary, charging service fees (spreads) to loan originators and to borrowers themselves who are seeking short-term financing. It offers investors three main avenues of return: short-term fixed-income plans (Fixed), plans with dynamic interest rates and liquidity (Dynamic), and specific loans for digital SMEs. One of the operational features that investors should monitor closely is its fee policy: withdrawing the profits that accumulate in the account is free of charge, but settling or withdrawing the principal early, before the loan matures, incurs a fee of 1% (early exit).
Corporate transparency and the management team present both positives and negatives. The principal partner and sole director of the organisation in Spain is Gunars Udris, a professional with extensive experience in alternative finance in the Baltic States. Udris is remembered in the investment community for having been a co-founder and director of Crowdestor, a Latvian platform that suffered serious incidents, severe delays and significant financial losses for investors. Although Udris severed his ties with that firm before its complete collapse, his direct involvement with FINFORTA means we must analyse every move with an extra measure of scepticism and rigorous risk management.
On the regulatory front, FINFORTA has a structure that raises concerns regarding investor protection. Although it was originally presented as being backed by a VASP (virtual asset service provider) registration in the Czech Republic, the definitive entry into force of the European MiCA Directive and the consequent end of the transitional period for this registration in July 2025 require much more robust and closely supervised licences than those they currently hold. As it lacks a licence as a Regulated Crowdfunding Service Provider (ECSP) regulated by ESMA, or a licence issued by the Czech National Bank (CNB) or the Spanish CNMV, FINFORTA operates in an environment with little administrative oversight and without a genuine financial regulator.
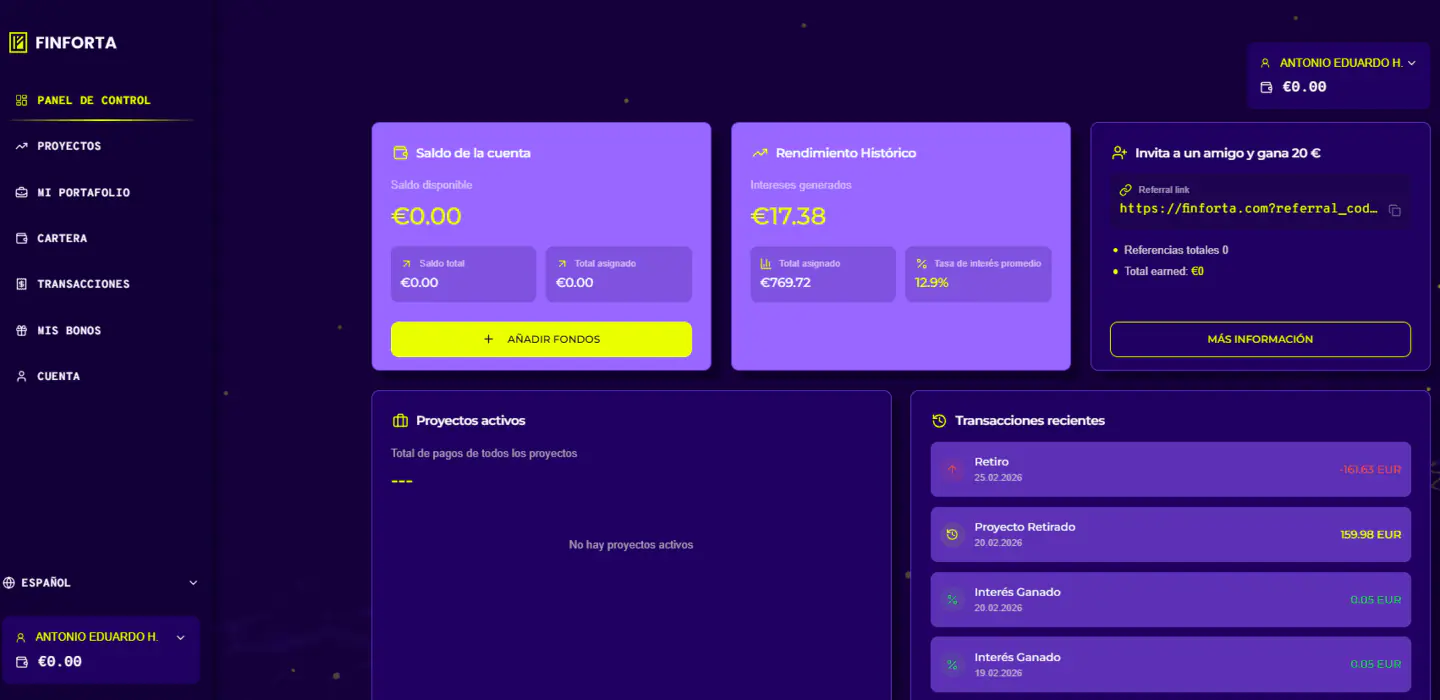
Our assessment on InvantAPPs places FINFORTA in the highest-risk segment due to the complete absence of a genuine buyback guarantee or a corporate provision fund, which means that the investor bears 100% of the default risk. Although it offers great flexibility for very short-term portfolios and attractive returns averaging 13% per annum, the lack of formal regulation prompts us to exercise extreme caution. In our performance tests on InvantAPPs, we recorded an actual return of 12.9% (IRR); however, as of July 2026, we decided to keep our net asset value at zero (€0 invested), preferring to channel capital towards platforms operating under the European ECSP regulatory framework.
Key points
Pros and cons
Experience and social proof
Social media activity
- Telegram
- YouTube
Alternatives to Finforta
Frequently Asked Questions
Is FINFORTA safe?
How much should I invest in FINFORTA?
How do I declare FINFORTA interest on my personal income tax return?
What happens if FINFORTA closes down?
What is the difference between the investment plans at FINFORTA?
What fees does FINFORTA charge investors?
Contact and support
- Low accessibility
Legal information
Corporate identity
Regulation and equipment
- The information is taken from public sources and may not be up to date. Always check the official website.
About the author
Antonio Hernández
Engineer, economist and founder of Invant APPs. I help you achieve financial freedom through smart investing and passive income.
Legal notice
Investing in crowdlending and crowdfunding involves risks, including the partial or total loss of the capital invested, and past performance is no guarantee of future results. The content on this site is for information purposes only and reflects our personal experience and opinion: it does not constitute financial or tax advice. Some links are affiliate links; the platform pays us a commission, which does not incur any cost to you nor does it influence our analysis.