Review of Robocash

Top 4 Liquidity
Top 6 Safety
Updated | October 2026
Yield
Up to 11%
Type
P2P Private Individuals
Risk
(7/10)
Bass
Liquidity
Secondary market
Regulated
No
Country
Croatia

InvantAPPs score

77/100

Breakdown by Category

Detailed scores for each area assessed

 0/20 
Significance within its sector
 0/10 
Ease of use and mobile app
 0/10 
Compound interest payable
 0/10 
Welcome bonus and referral bonus
 0/10 
Tax-friendly
 0/10 
Investment liquidity
 0/30 
Returns and fees

Features

Minimum investment:
10,00 €
Regulation:
Unlicensed
Withdrawal fee:
Free
Payment methods:
Instantaneous · SEPA
Type of investor:
Private individual/Business
Suitability test:
No
Geographical exclusions:
Only residents of the EU, the United Kingdom or Switzerland

Platform statistics

Assets under management
64.723.743,06 €
Updated: July 2026
Portfolio health:
Healthy
Loans per day: 99%
In recovery/recovery: 1%
41000
Investors

9

Years in active service
2017
Founded
Loans financed:
1.356.060.516,00 €
Average interest:
9.9%
Audited accounts:
Yes

InvantAPPs Portfolio

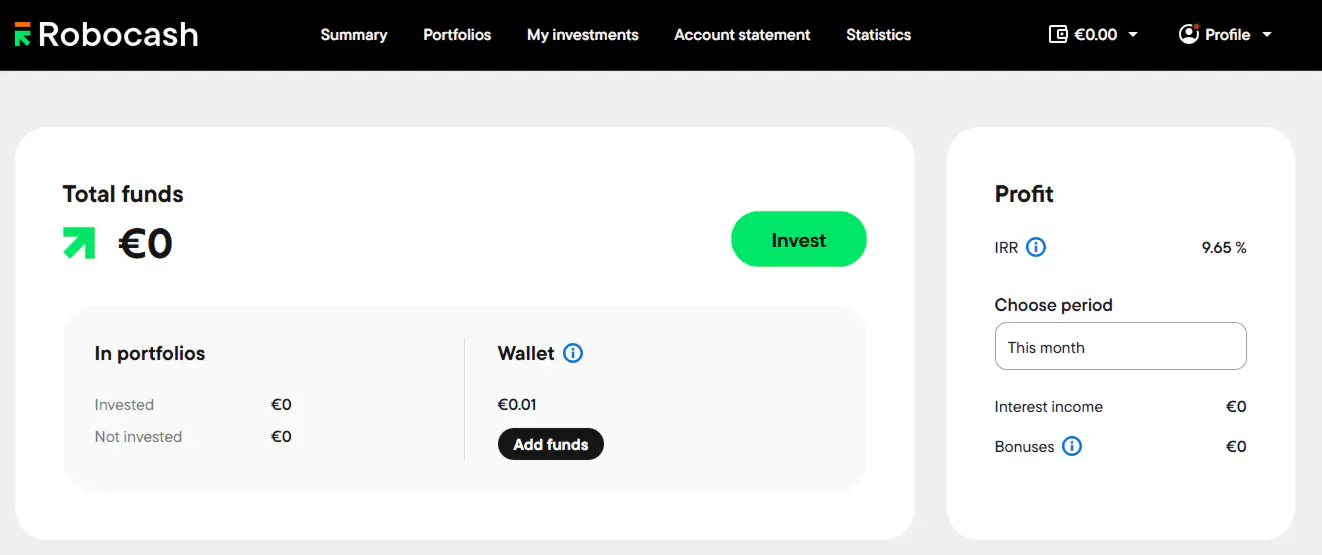
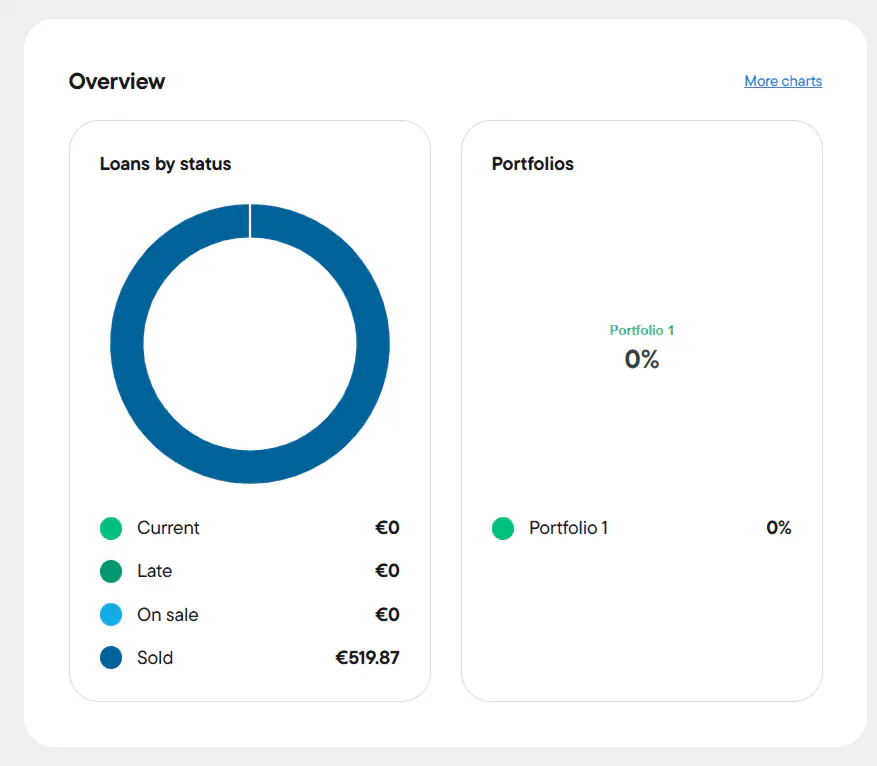
Total portfolio:
618,00 €

TIR:

9.65%
From:
March 2023
My current investment
Role in the portfolio:
Security
Suggested allocation:
3
-10

%

Dedication:
Bass
Surveillance:
Long term
Claim your bonus through our link
0.5% Additional
Join our Telegram community to ask questions and connect with other investors.

Taxation

Withholding tax:
It does not retain
Tax-friendly:
Yes
Model 720:
No
Income Tax Category:
Share capital
Tax certificate:
Yes
▸ Robo.cash indicates that it does not withhold taxes on interest; the investor must pay taxes and fulfill their fiscal obligations in accordance with the legislation of their country of residence. The platform offers a downloadable tax report for the selected period, detailing the gross and net income obtained, differentiating it from the generic account statement. For a resident taxpayer in Spain, interest is considered investment income and must be declared to the IRPF. Robo.cash does not specifically confirm the obligation or exemption of the Model 720, so it must be consulted according to the specific financial situation of the investor.

Liquidity

Second-hand market:
Manual
Early exit:
No
Average loan term:
12–36 months
Time to settle:
1–7 days
▸ The sale is made by manually selecting the loans and it remains pending for another investor to purchase them; Robo.cash typically indicates 1–7 days and does not charge a commission. When withdrawing funds from a One-click Portfolio, the invested funds must be sold on the secondary market; the platform indicates that it can usually take a few hours, but up to 30 days if there are expired loans. The available balance can be transferred later to the bank account within 2 business days according to the contractual terms. In April 2020, the platform announced that it planned to introduce the secondary market in May; no public evidence was found of a suspension of the secondary market during COVID-19 or the 2022 war. The terms indicate that the option to sell is only available when Robo.cash enables it and that the platform can restrict or disable access to its services.

Yield

Stated return:
Up to 11%
Self-investment:
Yes
Payment frequency:
Monthly

Regulation

License:
Unlicensed
▸ ROBOCASH d.o.o. (registration 081224371) is registered in Croatia. The platform declares that it is not regulated under any financial services license and that the P2P industry in Croatia is unregulated. Investments are not covered by any deposit insurance system, investment insurance, or compensation scheme. No valid ECSP authorization was found.

Guarantees and risk mitigation

A) Type of guarantee
▸ The loans are not backed by a specific real guarantee. The buyback is formalized in the Assignment Agreement: if the borrower defaults for more than 30 days, the originator must repurchase the credit by paying the principal and accumulated interest; UnaFinancial’s corporate guarantee is presented on the website and in the FAQ, but it has not been formalized in the legally binding documents consulted.
B) Stress scenario
▸ If Robo.cash goes bankrupt, the Assignment Agreements remain valid and the corresponding administrator will assume the management and collection of the loans. The Terms and Conditions also provide for stopping new operations, returning the available funds, and providing the investor with information about their transactions.
▸ When a loan exceeds 30 days in duration delay, the originator must repurchase the credit with the accumulated principal and interest. If the originator defaults, Robo.cash indicates that the buyback is at risk, although the investor retains collection rights against the borrower; the assumption of obligations by other companies in the group is stated in the FAQ, without any formalization identified in the legal document consulted.
C) Additional guarantees
Yes
(30 days)
Group
No
Yes
No
0.5% Additional
Claim your bonus through our link
0.5% Additional
Claim your bonus through our link

InvantAPPs Summary

What is Robocash?

Robocash It is a fully automated Croatian crowdlending platform that allows you to invest in consumer loans issued by the companies of the fintech group UnaFinancial. With an estimated net return of 9.7% per year and a minimum investment of just 10 euros, it is an ideal portal for investors looking for short-term yield passive income without the need to manually manage their portfolio. Its operations are exclusively directed at residents of the European Union, the United Kingdom, and Switzerland.

Founded in 2017 and with a historical loan volume exceeding 1.18 billion euros, it stands Robocash out for its 100% -percent passive investment model and the track record of its parent company, UnaFinancial. However, its main limitation is that it operates without a financial services license or ECSP regulation, meaning that the investor assumes a direct counterparty risk with the Croatian group. This concentration risk has been exacerbated by the holding’s increased leverage ratio and regulatory tensions in key subsidiaries, such as the temporary suspension of the license of Digido Finance Corp. in the Philippines. Despite these warnings and the fact that it does not retain taxes at source, we InvantAPPs consider that its buyback guarantee 30-day liquidity and the liquidity of its secondary market keep it as a valid alternative, although it is limited to a merely diversifying role in P2P portfolios with low exposure.

Key points

A completely passive and automated investment via its Auto-invest tool, with a minimum investment of just 10 euros.
There is a complete lack of financial regulation or an ECSP licence in Croatia, which means that investors are not covered by deposit guarantee schemes.
High concentration risk due to reliance solely on credit originators belonging to the UnaFinancial parent company’s holding company.
An estimated net return of 9.7% per annum, which is competitive within the sector but in line with the risk profile of its emerging credit markets.

Pros and cons

A mandatory 30-day buyback guarantee that is triggered automatically, returning the principal and any accrued interest.
An active, commission-free secondary market that allows you to recover liquidity from your capital within an estimated timeframe of 1 to 7 days.
There are absolutely no management, deposit or withdrawal fees, ensuring that your entire capital works without any hidden costs.
Risk of corporate insolvency at UnaFinancial due to the rise in its debt-to-equity ratio and regulatory instability affecting subsidiaries such as Digido in the Philippines.
Frequent instances of 'cash drag' reported by users due to a lack of available loans to meet high investment demand.
There is no real external diversification, as the 100% in the loan portfolio is vertically linked to the same business group.

Experience and social proof

Trustpilot

244 Reviews
3.9/5

ScamAdviser

0%
Trust score: 71/100
Updated: July 2026

Social media activity

🟡 Not very active
🟡 Not very active
🟡 Not very active
🟡 Not very active
⚪ No profile
🟡 Not very active

Frequently Asked Questions

Is it safe Robocash?

Robocash It does not have a regulated financial license or official supervision. Although it offers buyback guarantee a 30-day guarantee backed by UnaFinancial, the investor assumes the sole risk of the direct bankruptcy of this private holding company.

How much should I invest in Robocash?

It is advisable to allocate only a small portion of your P2P portfolio to this, ideally no more than 10% of your total capital. Due to the risk of concentration in a single business group, it should serve solely as a means of marginal diversification.

How to declare Robocash in the IRPF?

Interest earned is not subject to withholding tax and is taxed in Spain as investment income under the savings tax bracket (19% to 28%). The platform provides a downloadable annual tax certificate for use in your tax return.

What happens if it Robocash closes?

If the platform goes bankrupt, the rights to recover funds from UnaFinancial’s originators would, in theory, remain intact. However, as it is not subject to a regulatory framework nor does it have an independent winding-up plan, the process would be complex.

What is the 'cash drag' in Robocash?

This is the phenomenon whereby investors’ capital remains idle in their accounts without earning interest due to a lack of available loans. It often occurs when investor demand exceeds the platform’s supply.

Contact and support

Email: support@robo.cash
Telephone: +385 1344-58-18
They provide service in Spanish:
Yes
Live chat:
Yes
Telegram:
No
Response time:
1–24 hours
Official FAQ:

Corporate identity

Legal name:
ROBOCASH d.o.o. – Services
Country of registration:
Croatia
Registration code:
081224371
Registered office:
4 Franje Petračić Street, 10000 Zagreb, Croatia
Work email:
dataprotection@robo.cash

Regulation and equipment

Licence type:
Unlicensed
Management team
CEO and founder of UnaFinancial
Sergey Sedov
CFO and Deputy Managing Director
Ivan Adamovich
Legal Director
Janis Bogdasarovs
Verified profiles:
Yes

About the author

Antonio Hernández – Founder of InvantApps

Antonio Hernández

Engineer, economist and founder of Invant APPs. I help you achieve financial freedom through smart investing and passive income.

Legal notice

Investing in crowdlending and crowdfunding involves risks, including the partial or total loss of the capital invested, and past performance is no guarantee of future results. The content on this site is for information purposes only and reflects our personal experience and opinion: it does not constitute financial or tax advice. Some links are affiliate links; the platform pays us a commission, which does not incur any cost to you nor does it influence our analysis.