Review of Maclear

Top 7 Liquidity
No. 1 Profitability
Updated | October 2026
Profitability
Up to 16%
Type
P2B Business
Risk
(3/10)
High
Liquidity
Secondary market
Regulated
Yes
Country
Switzerland

InvantAPPs score

0/100

Breakdown by Category

Detailed scores for each area assessed

&nbsp0/20&nbsp
Significance within its sector
&nbsp0/10&nbsp
Ease of use and mobile app
&nbsp0/10&nbsp
Compound interest payable
&nbsp0/10&nbsp
Welcome bonus and referral bonus
&nbsp0/10&nbsp
Tax-friendly
&nbsp0/10&nbsp
Investment liquidity
&nbsp0/30&nbsp
Returns and fees

Features

Minimum investment:
50,00 €
Regulation:
Switzerland
Withdrawal fee:
Free
Payment methods:
Instantaneous · SEPA
Type of investor:
Private individual/Business
Suitability test:
Yes
Geographical exclusions:
Geographical exclusions: Residents of 44 European/EEA countries and the United Kingdom only; non-residents of North America, Asia, Africa, the Middle East, Oceania and CIS countries

Platform statistics

Assets under management
84.800.000,00 €
Updated: July 2026
Portfolio health:
Healthy
Current loans: 100%
In arrears/recovery: 0%
46012
Investors

4

Years in active service
2022
Founded
Loans financed:
126.268.224,00 €
Average interest:
15.2%
Audited accounts:
Yes
Regulatory licence:
Switzerland

InvantAPPs Portfolio

Total portfolio:
16.880,00 €

TIR:

17.60%
From:
January 2025
My current investment
Role in the portfolio:
Profitability
Suggested allocation:
3
-10

%

Dedication:
Bass
Surveillance:
Long term
Claim your bonus through our link
Up to 12% in cashback
Join our Telegram community to ask questions and connect with other investors.

Videos about Maclear

Taxation

Withholding tax:
It does not retain
Tax-friendly:
Yes
Model 720:
No
Income Tax Category:
Share capital
Tax certificate:
Yes
Notes: Maclear indicates that it does not withhold or deduct taxes and that the investor must declare their income according to the legislation of their country of residence. It offers a downloadable PDF tax report from Statements → Tax, configurable for any period, which includes interest cashback, rewards, bonuses, and secondary market results. The report contains aggregated data and does Maclear not confirm that it is an annual tax certificate compatible with the Spanish declaration. The platform also does not report the income to the tax authorities. if the average balance of the last quarter or the balance of your funds at the end of the year (summed with other financial assets outside Spain) exceeds the legal threshold of 50,000 €, you will be required to file Form 720 with the Tax Authority

Liquidity

Early exit:
Yes
Type of early exit:
project
Penalty for early exit:
2.5% (mandatory deduction to replenish the reserve fund)
Average loan term:
6–14 months
Time to settle:
97% within 7 days
Notes: The investor manually lists the investment on the secondary market, at par or at a discount of up to 50%. The listing remains active for up to 14 days; if no buyer is found, it is automatically removed without commission and the investment continues until maturity. The sale is not guaranteed. Official statistics indicate a median sale time of approximately 3 hours and a 100% of sales within 14 days for the closed cohorts from June 2025 to March 2026.

Profitability

Stated return:
Up to 16%
Self-investment:
Yes
Payment frequency:
Monthly

Regulation

Regulatory body:
PolyReg Services GmbH SRO
Competent authority:
Not available
Entry in the register:
Country of regulation:
Switzerland
Regulated since:
July 2022
Notes: Maclear AG operates as a non-bank financial intermediary under Swiss law and is a member of PolyReg Services GmbH, a self-regulatory organisation recognised and supervised by FINMA. It is not directly supervised by FINMA, does not hold a European ECSP authorisation, and Switzerland does not issue a specific crowdlending licence; membership of PolyReg provides supervision primarily in accordance with Swiss anti-money laundering regulations.

Guarantees and risk mitigation

A) Type of guarantee
Pledge (movable property)
▸The Maclear guarantees operate via an internal provision fund that immediately advances the capital to prevent temporary delays in your monthly payments. In the event of a definitive default, a specialist agent enforces the physical collateral (such as commercial pledges or mortgages) through legal proceedings under Swiss commercial law. These assets are valued conservatively, with discounts of up to 50%, to ensure that a swift sale at auction fully covers investors’ principal.
B) Stress scenario
▸Users’ liquid funds are protected under a strict system of segregated bank accounts that are independent of the fintech’s operational accounts; consequently, uninvested capital is excluded from any hypothetical insolvency proceedings. Furthermore, as the company is currently undergoing the regulatory approval process, uninvested cash is backed by European compensation schemes that guarantee up to €20,000 per investor in the event of institutional insolvency.
▸In the event of a catastrophic scenario that exceeds the coverage provided by the platform’s provision fund, legal claims and enforcement proceedings are immediately initiated. MACLEAR’s collateral agent is responsible for enforcing, realising and selling, either on the secondary market or through a forced auction, all the collateral and tangible assets underpinning the loan in order to repay the principal to investors.
▸N/A
C) Additional guarantees
No
Yes
Yes
No
Up to 12% in cashback
Claim your bonus through our link
Up to 12% in cashback
Claim your bonus through our link

InvantAPPs Summary

What is Maclear?

MACLEAR (maclear.ch) is a crowdfunding platform for corporate debt that connects investors with SMEs in the European Union, particularly in the Baltic states. Founded in Wallisellen by risk management experts, it allows investments from as little as €50, with an average annual return of 14.6% and terms of 12 months. Backed by real assets and a liquid secondary market, we assess its institutional security, its provision fund and its regulatory roadmap.
It is essential to analyse genuine reviews of Maclear and understand how it works before investing your capital.

Here at InvantAPPs, we have prepared a fully transparent assessment of this Swiss corporate debt platform. Let’s start by addressing the elephant in the room head-on: in our recent interview with Iván Marchena, the platform’s CCO, we laid our cards on the table. Maclear is based in Switzerland and is supervised by PolyReg SRO strictly in accordance with anti-money laundering (AML) regulations. As it is not part of the European Union, it does not automatically hold an EU passport. The CNMV’s notification does not indicate fraud or insolvency; it simply reflects this jurisdictional reality. To resolve this and expand freely throughout the eurozone, the fintech company has already formally submitted its application for the European ECSP licence, anticipating official approval within an optimistic timeframe of 6 to 8 months.

This rigorous regulatory framework is complemented by long-awaited milestones in transparency within our sector. Although there had been concerns in previous months regarding the lack of public reports, in early June 2026 the company successfully published its audited compliance report for the 2024 financial year, following the completion of a complex data migration to advanced CRM systems. The audited accounts for 2025 are scheduled for release in the autumn of this year. At InvantAPPs, we find it very reassuring to know that the founders, Denis Ustjev and Aleksandr Lang, have a background in auditing and economic-actuarial analysis in Switzerland. Their risk philosophy is uncompromising: they apply a 40-point filter that screens out 90% of applications from SME borrowers. Furthermore, when valuing collateral (machinery, lorries or industrial premises), they conservatively apply a discount of between 25% and 50%, simulating an urgent sale. That is why you will see projects with an apparent Loan-to-Value (LTV) ratio of 84% or even in excess of 100%; it is deliberately undervalued so that, in the event of default, the judicial liquidation of the collateral will cover the investors’ principal without any surprises.

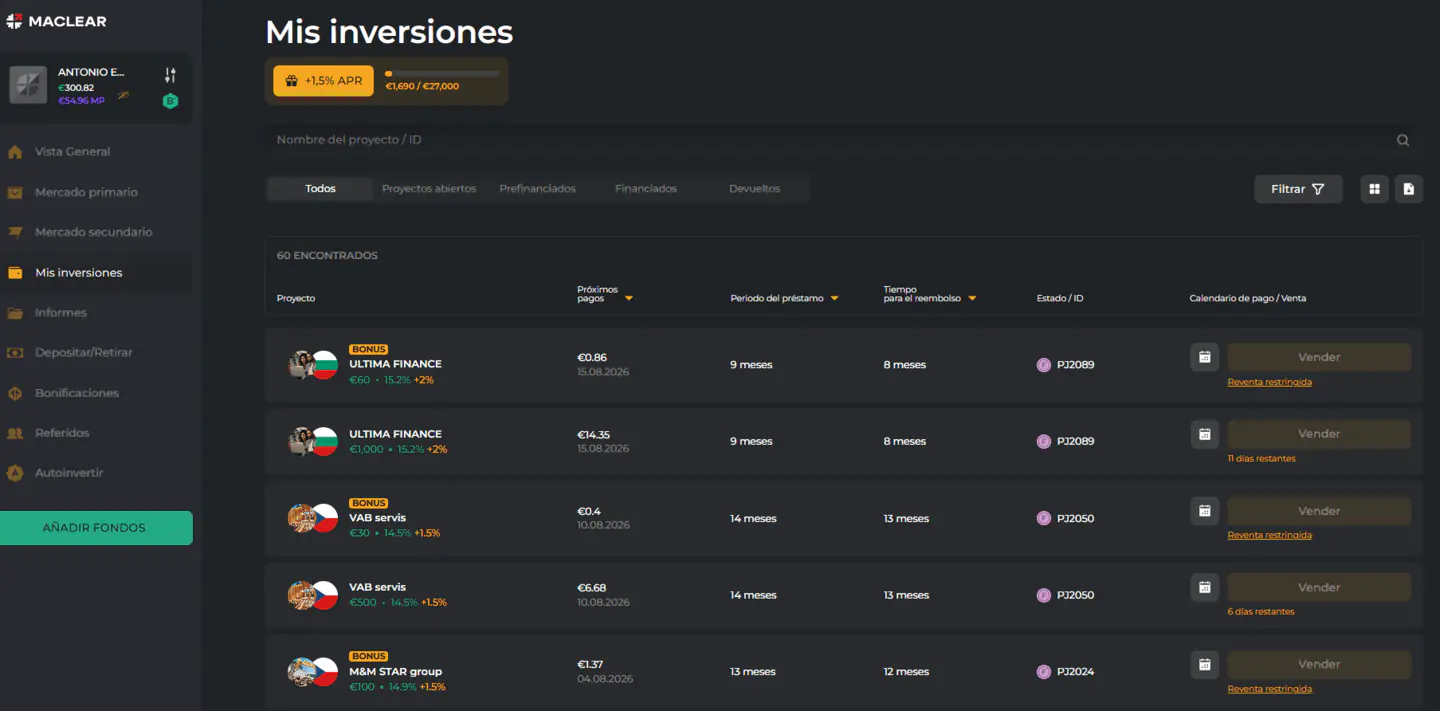
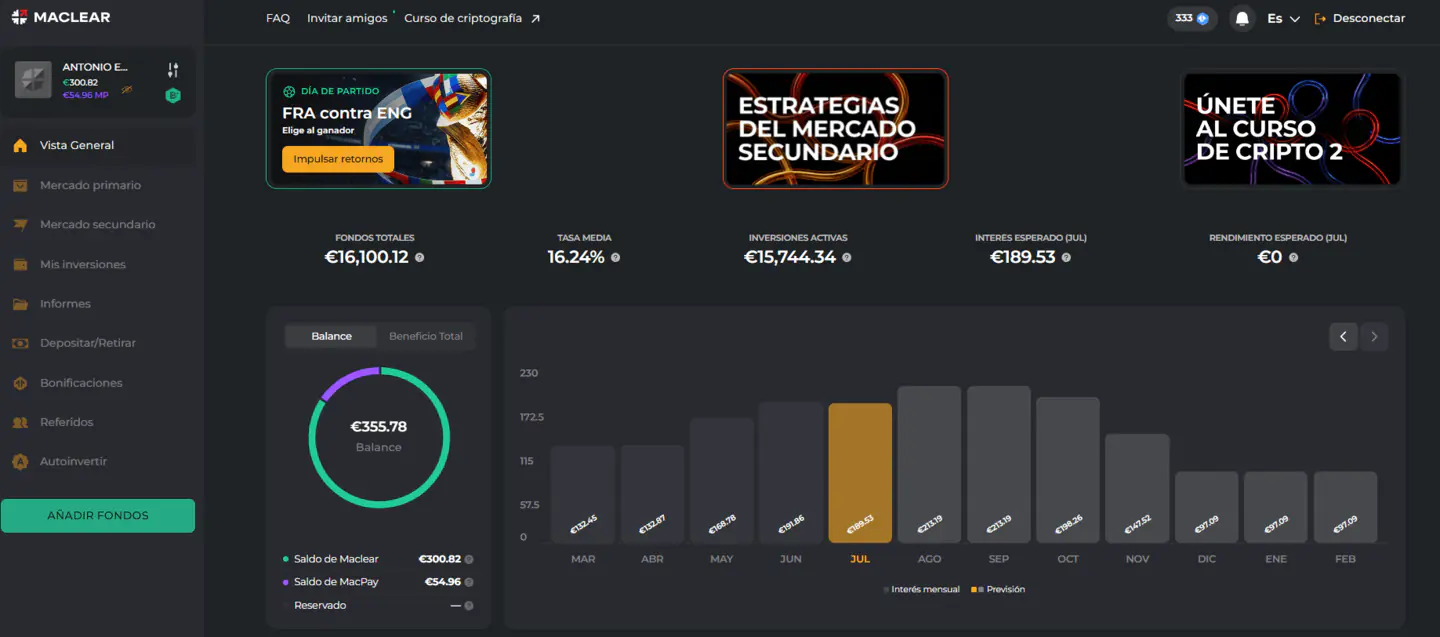
Our track record with this asset underpins this strength. We have gone from managing €10,000 to consolidating nearly €13,000 in assets in the account, with the clear aim of reaching the €15,000 threshold to unlock the Beta Plus level (+2.0% in extra interest) and set our sights on the €40,000 mark for Alpha status. In terms of debt recovery, the platform’s track record is impeccable. The only high-profile delay in its history (involving the Italian company Vibroedal for €150,000 in July 2025) was resolved in just two months through a private repayment agreement that returned 100% of the principal to users. This was made possible by its active Provision Fund, which is funded by a 2% fee charged to borrowers and the 2.5% commission paid by sellers on the secondary market. Thanks to this liquidity buffer, which brings forward payments, we have never experienced a single day’s delay in monthly interest payments.

If you want to know how to start investing in Maclear whilst maximising your returns, the channel’s strategy is precise: split your capital into €500 chunks to activate its aggressive welcome package (a €15 sign-up bonus, a +3% return for the first 90 days and a direct cashback of €30 per block), boosting your return on your first trades to as much as 26%. However, bear in mind the tax rules in Spain: as there is no withholding tax, you must declare these capital gains annually on an accrual basis in box 0027 of your income tax return, regardless of whether the money is being passively reinvested via their Auto-Invest feature. Finally, we have an exclusive scoop: MACLEAR is expanding on-chain by merging with its sister Web3 protocol, Aens (Aliens). Through the Base Layer 2 network, they will launch a 'Crypto Lending' service that will allow users to pledge Bitcoin or Ethereum to receive USDC at a floating rate of 3% and reinvest it in the European real economy, opening up the platform to global investors from Latin America and around the world.

Key points

Leading average annual returns of between 14.6% and 16.0%, combined with a massive secondary market that sees trades settle in just 3 hours on average.
Mitigation of default risk through security interests and physical collateral under Swiss law, valued at ultra-conservative discounts ranging from 25% to 50%.
Supervised by PolyReg SRO in Switzerland, with a formal application for an ECSP licence currently being processed in order to have the CNMV’s information notice lifted.
It has an active provision fund accumulated through primary (2%) and secondary (2.5%) borrower fees, which eliminates delays in investors’ accounts.
The obligation to pay tax annually in Spain under the accrual basis (rather than the cash basis), coupled with the risk of having to submit Form 720 if the balance in Switzerland exceeds €50,000 in cash.

Pros and cons

High returns of 14.6% in average annual interest, with monthly settlement and payment of instalments to generate stable cash flows.
An exceptionally liquid secondary market that saw trading volumes of 1.3 million euros and 5,000 transactions in a single month, enabling rapid exits.
Active provision fund (funded by 2% from origination and 2.5% from resale) which acts as a liquidity buffer to cover borrower shortfalls.
A thorough risk assessment based on due diligence involving 40 financial KPIs, which immediately rules out 90% from the applicant SMEs.
A cumulative welcome bonus scheme that provides up to 9% in extra returns during the first 90 days, in blocks of €500.
Temporary suspension of the European ECSP passport, operating under a CNMV warning from May 2026 until the regulatory transition is completed in 6–8 months.
Penalty for early redemption on the secondary market in the form of a fixed fee of 2.5%, payable exclusively by the selling investor.
The minimum threshold for manual investment is set at €50 per commercial project, which limits the scope for fine-grained diversification compared with the €10 minimums in the P2P sector.
Risk of a protracted judicial liquidation process for niche assets (specialised machinery) which are subject to price penalties of up to 50% in compulsory sales.
You are legally obliged to complete Form 720 with the AEAT if the total value of your assets held abroad exceeds the threshold of €50,000.

Experience and social proof

Trustpilot

775 Reviews
4.5/5

ScamAdviser

0%
Trust score: 96/100
Updated: July 2026

Social media activity

🟡 Not very active
🟡 Not very active
🟢 Very active
🟡 Not very active
⚪ No profile
🟡 Not very active

Alternatives to Maclear

If Maclear doesn’t suit your profile, here are the highest-rated alternatives in the sector
0/100
Profitability:
Up to 16%
Risk:
High
(4/10)
Regulated:
No
0/100
Profitability:
Up to 15%
Risk:
Medium
(5/10)
Regulated:
Yes
0/100
Profitability:
From 15.1%
Risk:
Medium
(6/10)
Regulated:
Yes

Frequently Asked Questions

What is Maclear and what sort of projects does it invest in?

It is a Swiss P2B crowdlending platform that finances corporate debt for small and medium-sized enterprises in the European Union, with a focus on the business sector in the Baltic states. It offers an average annual interest rate of 14.6% on loans secured by physical collateral.

Is MACLEAR safe?

MACLEAR operates as a financial intermediary under the SRO PolyReg in Switzerland (which specialises in anti-money laundering). It does not hold a banking licence or offer a buy-back guarantee; its security relies on physical collateral and credit analysis.

What does the CNMV warning issued in May 2026 mean?

This notice clarifies that Maclear operates outside the EU regulatory framework, as it is a Swiss company supervised by PolyReg SRO. This does not imply fraud; the fintech company has already formally applied for the European ECSP licence and expects to obtain it and achieve full regulatory compliance within 6 to 8 months.

How much should I invest in MACLEAR?

Due to its high-risk profile resulting from the absence of a buy-back guarantee, it is recommended that you limit your exposure to MACLEAR to 5% or 10% of your total crowdlending portfolio, whilst always diversifying with a minimum of 50 euros per project.

How do I declare MACLEAR interest on my personal income tax return?

Interest earned is taxed in Spain as investment income (19% to 30%). MACLEAR does not apply any withholding tax nor issue an official annual tax certificate, so you must declare this income using their PDF report.

What happens if MACLEAR closes?

If MACLEAR ceases trading, your capital is protected thanks to the segregation of accounts under Swiss law. The loan agreements and physical collateral provided by SMEs remain in force and would be managed by an external liquidator.

Does MACLEAR charge investors any fees?

MACLEAR is a platform with no registration, deposit or withdrawal fees for investors. The only charge is a 2.5% sales fee on the principal if you decide to sell early on the secondary market.

Does Maclear have a provision fund or a share buyback scheme?

It does not offer a traditional corporate buy-back guarantee, but it does have an active Provision Fund. This fund is financed by a 2% of each loan applied for and a 2.5% resale commission, and is used to advance capital and cover arrears immediately. Its only historical payment delay (Vibroedal, amounting to €150,000) was recovered in full within two months.

Contact and support

Email: support@maclear.ch
They provide service in Spanish:
Yes
Live chat:
Yes
Telegram:
Yes
Rating:
4/5
Response time:
1–24 hours
Official FAQ:

Corporate identity

Legal name:
Maclear AG
Country of registration:
Switzerland
Registration code:
CHE-115,674,165
Registered office:
Richtistrasse 7, 8304 Wallisellen, Switzerland
Work email:
info@maclear.ch

Regulation and equipment

Licence type:
Switzerland
Management team
CEO & Co-Founder
Denis Ustjev
CFO & Co-Founder
Aleksandr Lang
Chief Accountant
Simon Brauchli
Verified profiles:
Yes

About the author

Antonio Hernández – Founder of InvantApps

Antonio Hernández

Engineer, economist and founder of Invant APPs. I help you achieve financial freedom through smart investing and passive income.

Legal notice

Investing in crowdlending and crowdfunding involves risks, including the partial or total loss of the capital invested, and past performance is no guarantee of future results. The content on this site is for information purposes only and reflects our personal experience and opinion: it does not constitute financial or tax advice. Some links are affiliate links; the platform pays us a commission, which does not incur any cost to you nor does it influence our analysis.